Loan Finance Online Business Loan Repayment Calculator
Estimate repayments with our Business Loan Calculator. Compare finance options, tailor loan terms, and plan with confidence for your business growth.
Calculator results are estimates only and not quotes. Actual quotes will be provided by licensed brokers after you submit an enquiry.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.). To find out if you qualify ... and for a free, personalised interest rate and repayment quote,
please CLICK HERE
Business Loan Amortisation Calculator
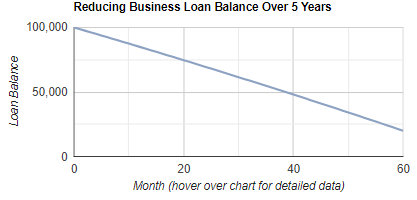
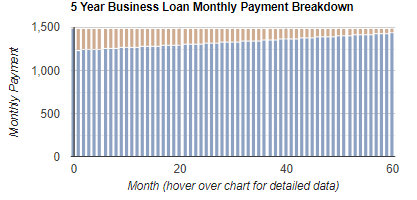
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
In the bustling world of entrepreneurship, small business loans often act as the backbone that supports growth and sustainability. Understanding the array of loan options available is imperative for business owners in Australia, ensuring that they can make informed decisions that align with their objectives. - read more
Australian lenders assess loan applications by looking at income, expenses, credit history, existing debts, security, documentation and whether the loan appears affordable for the borrower's circumstances. - read more
If you're looking to buy your first home, starting to save early is one of the smartest financial moves you can make. By beginning to save when you're young, you give yourself a head start in accumulating the necessary funds to make a deposit on a house. This proactive approach has numerous benefits that extend beyond just having more money in the bank. - read more
Home loans in Australia involve more than choosing an interest rate. Borrowers need to understand deposits, borrowing capacity, repayments, fees, settlement and features such as offset accounts and redraw facilities before comparing options. - read more
Refinancing is moving back into focus for Australian borrowers as households and small businesses look for ways to regain control over higher repayment commitments. Recent lending market updates suggest more borrowers are no longer simply waiting for broad interest rate relief; they are actively reviewing whether their existing loan still fits their income, expenses and longer-term plans. - read more
The latest home lending indicators point to a property finance market that is still moving, even with borrowers facing high living costs and careful lender scrutiny. Investor activity has been one of the stronger parts of the market, adding another layer of competition for owner-occupiers and first-home buyers trying to secure finance. - read more
The Reserve Bank of Australia’s latest decision to leave the cash rate unchanged has given borrowers another holding pattern rather than clear relief. For households and small businesses, the key message is that borrowing costs may remain elevated until policymakers are more confident inflation is moving sustainably lower. - read more
Australia's mortgage market is showing more signs of competition, with a broader group of lenders adjusting fixed home loan pricing as expectations grow that the next major move in interest rates may eventually be down. For borrowers, the shift is encouraging, but it is not a simple signal to lock in the first lower rate that appears. - read more