Explore potential car finance repayments with our Car Loan Repayment Calculator. Test different loan amounts, interest rates and repayment periods, and view detailed amortisation charts to see how repayments, interest costs and loan balances may change over time.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations. Actual repayments and costs may differ.
Car Loan Details:
Important!
Car Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Loan Amortisation Calculator
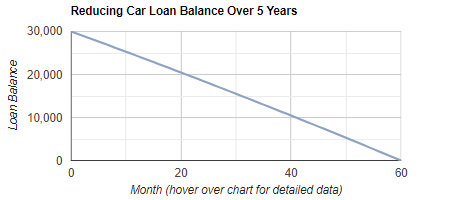
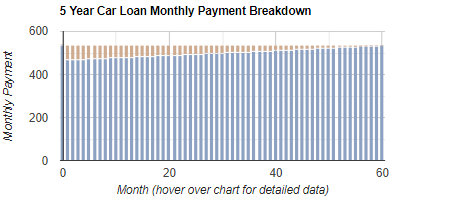
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Car Loan Repayment Calculator
Our Car Loan Repayment Calculator helps you estimate repayments for an Australian car loan and see how your balance, interest and principal change over time. It is important because small changes to the loan amount, term or interest rate can materially affect your monthly budget and the total interest you pay. The amortisation charts make it easier to compare scenarios and choose a structure you can afford with confidence.
General information only: This calculator provides an estimate and does not take into account your objectives, financial situation or needs. Results are indicative and your actual interest rate and repayments will depend on the lender, your credit profile and the final loan contract (including fees and conditions).
How to complete each section for the best result:
1. Purchase Price
Enter the vehicle purchase price as a whole number (no decimals or commas). If you plan to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts here so the estimate better reflects your likely loan size.
2. Deposit or Trade-in Value
Enter your cash deposit and/or trade-in value as a whole number. A higher deposit reduces the amount financed and usually lowers repayments and total interest.
3. Term of Loan (Years)
Select the number of years you want to repay the loan over. Shorter terms usually mean higher repayments but lower total interest. Longer terms can reduce monthly repayments but typically increase total interest paid.
4. Interest Rate (% per annum)
Select an interest rate to simulate. If you have a quote, choose the closest rate. If comparing options, run multiple calculations to see the impact of different rates.
5. Calculate
Click calculate to generate your results and charts.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability, leaving buffer for running costs and rate changes.
2. Amortisation charts: One chart shows the loan balance reducing over time; the other shows how early repayments are often interest-heavy and gradually shift toward principal repayment.
3. Comparison planning: Re-run the calculator with different terms, deposits and rates to identify a repayment level and total interest outcome that suits your budget.
Financial independence means having enough income to pay for one's living expenses without relying on a traditional job. In Australia, this concept is not just a dream but a necessity for many who aspire to a life free from financial stress. It offers the freedom to make choices about how you want to live your life, from retiring early to pursuing passions and interests without monetary constraints. - read more
Personal loans can help Australians fund expenses such as a car, renovation, travel, medical costs or debt consolidation. This guide explains how they work, the main costs, common eligibility factors and what to consider before applying. - read more
Home loans in Australia involve more than choosing an interest rate. Borrowers need to understand deposits, borrowing capacity, repayments, fees, settlement and features such as offset accounts and redraw facilities before comparing options. - read more
In the bustling world of entrepreneurship, small business loans often act as the backbone that supports growth and sustainability. Understanding the array of loan options available is imperative for business owners in Australia, ensuring that they can make informed decisions that align with their objectives. - read more
Australia’s home lending market has delivered a sharp warning signal, with new Australian Bureau of Statistics figures showing the number of new dwelling loan commitments fell 15.0 per cent in the September quarter 2026. The fall was led by investors, but the broader message for borrowers is wider: higher rates, changing tax settings and softer property expectations are now influencing both lender caution and buyer confidence. - read more
The Reserve Bank of Australia’s 3 November decision to lift the cash rate by 25 basis points to 4.85 per cent has quickly shifted from monetary policy headline to household and business budgeting issue. Major lenders have moved to raise variable mortgage rates and savings rates from mid-November, reinforcing that borrowers now need to think less about a single repayment change and more about how much buffer remains in their overall loan commitments. - read more
Fresh evidence of delayed payments across Australian business is a timely warning for owners weighing up finance decisions. ABC News reported this week that small firms are dealing with a difficult mix of higher operating costs, regulatory changes and slower customer payments, while CreditorWatch’s September Business Risk Index showed one in 10 invoices over the past three months was more than 60 days overdue. - read more
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more
Deed in Lieu of Foreclosure: A deed instrument in which a borrower conveys all interest in a property to the lender to satisfy a loan that is in default and avoid foreclosure.