Loan Finance Online Bike Loan Repayment Calculator
Calculate motorcycle loan repayments in seconds with our Bike Loan Calculator. Compare finance options and plan your ride with confidence.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations. Actual repayments and costs may differ.
Bike Loan Details:
Important!
Bike Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Bike Loan Amortisation Calculator
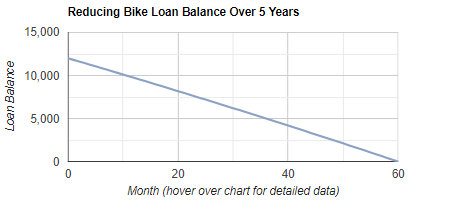
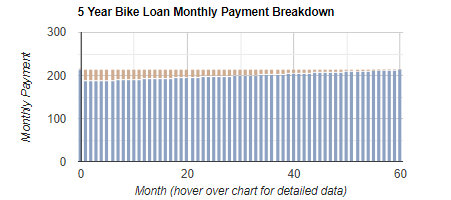
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Bike Loan Repayment Calculator
Our Bike Loan Repayment Calculator is designed to estimate your motorcycle loan repayments in seconds, so you can compare bike finance options and plan your budget before you commit. It is important because small changes to loan size, term length and interest rate can materially change your monthly repayment and the total interest you pay over the life of the loan.
This calculator provides estimates only and is not personal financial advice. Results do not take into account your objectives, financial situation or needs. Interest rates and fees vary by lender and your individual circumstances, and your final rate can only be confirmed after an application is assessed.
How to complete the form for the best result:
1. Purchase Price
Enter the bike purchase price as a whole number (no dots or commas). If you expect to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts in the figure you enter so the estimate better reflects your likely loan amount.
2. Deposit or Trade-in Value (if applicable)
Enter your deposit or trade-in value as a whole number. If you have no deposit, enter 0. A higher deposit generally reduces the amount borrowed and can reduce interest paid over time.
3. Term of Loan (Years)
Select a term between 1 and 7 years. Longer terms typically reduce monthly repayments but can increase the overall cost of the loan due to more interest over time. Choose a term that fits your cash flow, not just the lowest repayment.
4. Interest Rate (% per annum)
Select an interest rate for the simulation. If you are unsure, test a conservative higher rate to see whether repayments remain affordable.
5. Calculate
Click calculate to generate your estimated repayment and amortisation visuals.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a starting point for budgeting, then stress-test by increasing the rate or reducing your deposit to see how sensitive repayments are.
2. Amortisation graphs
Review the loan balance chart to understand how quickly you reduce what you owe, and the interest versus principal chart to see how much of each repayment goes to interest compared with reducing the loan balance over time.
If you're looking to buy your first home, starting to save early is one of the smartest financial moves you can make. By beginning to save when you're young, you give yourself a head start in accumulating the necessary funds to make a deposit on a house. This proactive approach has numerous benefits that extend beyond just having more money in the bank. - read more
Car loans can help Australians buy a new or used vehicle, but the structure of the finance matters. This guide explains secured and unsecured vehicle finance, repayments, balloon payments, fees, eligibility and key checks to make before applying. - read more
In the bustling world of entrepreneurship, small business loans often act as the backbone that supports growth and sustainability. Understanding the array of loan options available is imperative for business owners in Australia, ensuring that they can make informed decisions that align with their objectives. - read more
In today's fast-paced world, financial literacy is more important than ever. For Australians, being financially literate means confidently navigating through personal finances, investments, and economic changes. It empowers individuals to make informed decisions about their money, which can lead to greater financial security and peace of mind. - read more
Australia’s home lending market has delivered a sharp warning signal, with new Australian Bureau of Statistics figures showing the number of new dwelling loan commitments fell 15.0 per cent in the September quarter 2026. The fall was led by investors, but the broader message for borrowers is wider: higher rates, changing tax settings and softer property expectations are now influencing both lender caution and buyer confidence. - read more
The Reserve Bank of Australia’s 3 November decision to lift the cash rate by 25 basis points to 4.85 per cent has quickly shifted from monetary policy headline to household and business budgeting issue. Major lenders have moved to raise variable mortgage rates and savings rates from mid-November, reinforcing that borrowers now need to think less about a single repayment change and more about how much buffer remains in their overall loan commitments. - read more
Fresh evidence of delayed payments across Australian business is a timely warning for owners weighing up finance decisions. ABC News reported this week that small firms are dealing with a difficult mix of higher operating costs, regulatory changes and slower customer payments, while CreditorWatch’s September Business Risk Index showed one in 10 invoices over the past three months was more than 60 days overdue. - read more
Financial hardship support is back in the spotlight across Australia’s lending market, with regulators and consumer advocates paying closer attention to how banks and non-bank lenders respond when borrowers ask for help. For households and small business owners already dealing with higher living costs, tax obligations, insurance premiums and uneven cash flow, this is more than a compliance story. It is a practical reminder that loan stress should be addressed before it becomes a missed-payment pattern. - read more